Definition
Cumulative Distribution Function
The cumulative distribution function
of a random variable (continuous or discrete) is defined as: Properties:
is bounded, i.e.: is monotonically increasing, i.e.: is right-continuous: - Left/right asymptotes are:
Discrete vs Continuous
Discrete
The cumulative distribution function
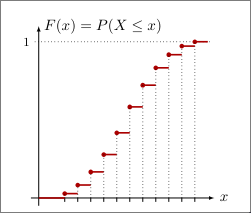
Let
From that, we get:
Continuous
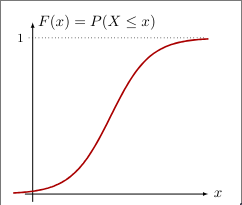
Let
From that, we get:
and the density is the cumulative distribution function’s derivative:
Inverse
One often needs the inverse function of a cdf
Therefore, we need the generalised inverse of